

 0
 0
India’s SME IPO market continues to witness numerous exceptional occasions. In this context, the Q-Line Biotech IPO has made its entry; it’s being hailed as the biggest IPO ever to be listed on India’s SME market, with a measurement of roughly INR 214.85 crore. Prior to this, the title was held by Danish Power, which had a problem measurement of INR 197.90 crore.
The firm secured a big pre-IPO placement on 13 May 13, 2026. Ace investor Vikas Vijaykumar Khemani invested INR 14.94 crore to amass 4,35,502 fairness shares on the higher worth band of INR 343 per share. Total pre-IPO funds raised amounted to INR 27.44 crore from outstanding entities, together with Calliope Capital Advisors LLP (INR 8.00 crore) and Sahastraa Advisors (INR 1.00 crore), successfully lowering the web contemporary situation measurement to 62,53,200 fairness shares. So, let’s proceed to conduct the Q Line Biotech IPO evaluation and discover out simply how a lot potential it holds.
Q Line Biotech IPO Analysis: Business Overview
Q-Line Biotech is an built-in participant within the In-Vitro Diagnostics (IVD) area. The firm is concerned in growing, manufacturing, and advertising and marketing an intensive array of diagnostic reagents, consumables, fast take a look at playing cards, point-of-care (POC) units, and automatic laboratory tools. The firm operates on a business-to-business (B2B) mannequin, and caters to industrial diagnostic laboratories, hospitals, medical schools, and public well being networks.
Q Line Biotech’s enterprise mannequin evaluation reveals that Reagents stay its major money cow, contributing 68.76% of complete operational revenues (INR 159.43 crore) within the 9M FY26. Within this section, Clinical Chemistry reagents characterize the biggest sub-category, producing 65.75% of complete reagent revenues.
Revenue Breakdown by Product Category
| Segment (% of Revenue) |
FY 2023 | FY 2024 | FY 2025 | 9M FY 2026 |
| Reagents | 131.47 (71.94%) |
135.80 (66.68%) |
176.40 (56.27%) |
159.43 (68.76%) |
| Instruments | 39.09 (21.39%) |
56.70 (27.84%) |
114.94 (36.64%) |
63.10 (27.22%) |
| Consumables | 10.40 (5.69%) |
6.08 (2.98%) |
14.15 (4.47%) |
7.03 (3.03%) |
| Services (AMC) | 1.77 (0.97%) |
5.07 (2.49%) |
8.22 (2.62%) |
2.29 (0.99%) |
| Total | 182.74 | 203.65 | 313.71 | 231.85 |
In FY 2023, 100% of the diagnostic devices bought by the corporate have been sourced through worldwide buying and selling. However, by leveraging Technology Transfer Agreements (TTAs) with European companions and increasing its native manufacturing infrastructure throughout 4 amenities (three in Lucknow, one in Delhi), manufactured devices grew to account for 53.24% of its instrument section income in 9M FY 2026.
Read Also: Biggest SME IPOs Of All Time
Manufacturing Pipeline
The firm presently manufactures the Selectra Pro M (a medium-throughput totally computerized scientific chemistry analyzer) regionally. Its future progress depends closely on commercialising its present prototype pipeline underneath the “Make in India” initiative:
- Selectra Pro XL: A high-throughput totally computerized scientific chemistry analyzer designed for big hospital laboratory networks (superior prototype stage).
- Medonic M20: A 3-part haematology analyzer that has cleared regulatory approvals; industrial manufacturing is anticipated to go dwell in Q2 FY 2026-27.
- Innolyte & Slide Stainer: Indigenously engineered programs designed to broaden the corporate’s proprietary expertise footprint in secondary lab tiers.
Industry Context
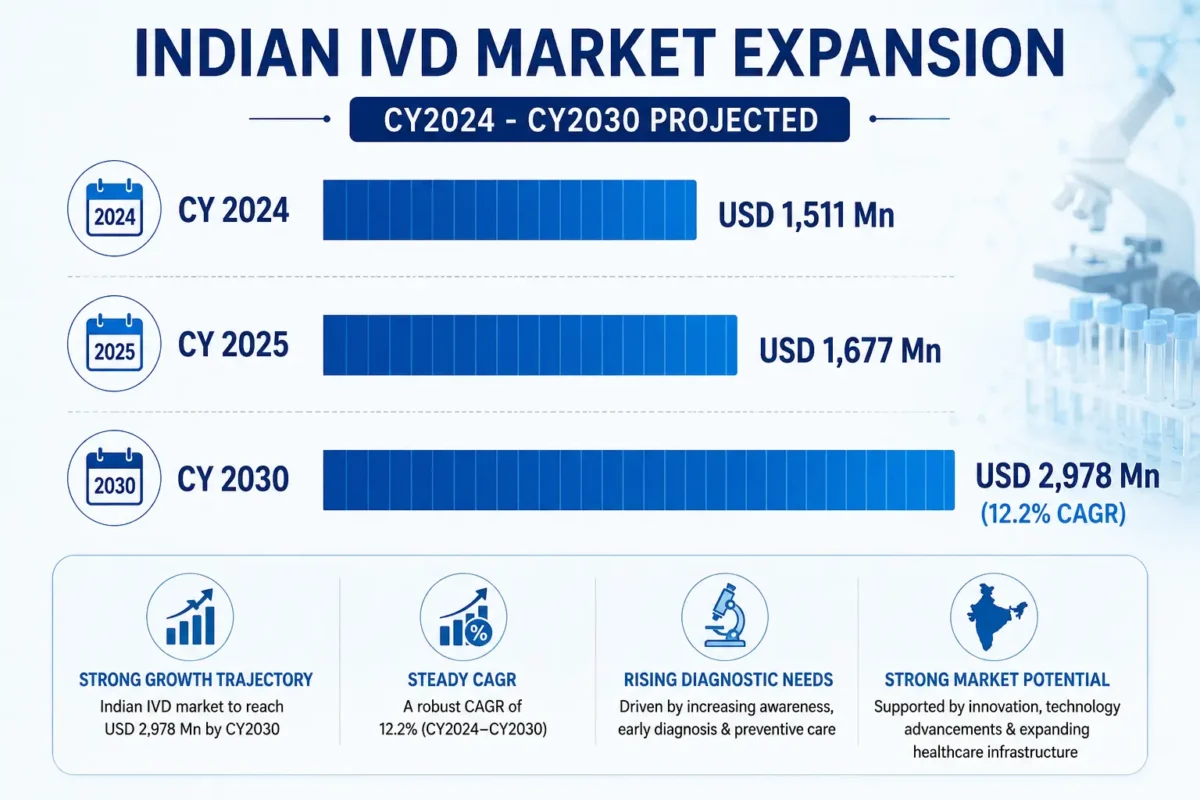
The Indian In-Vitro Diagnostics (IVD) market goes via a structural transformation. According to knowledge compiled from CareEdge Research, the home IVD market was valued at USD 1,511 million in CY2024 and expanded to USD 1,677 million in CY2025. Driven by an growing older demographic, a rising burden of non-communicable life-style ailments (equivalent to diabetes and cardiovascular circumstances), and an specific systemic shift from reactive “sick care” to proactive, wellness-oriented preventive diagnostics, the market is projected to achieve USD 2,978 million by CY2030, compounding at a CAGR of 12.2%.
Several macroeconomic indicators reinforce Q-Line’s working setting:
- Consumable Dominance: Reagents and take a look at kits characterize 66% of the general product market share resulting from recurring consumption necessities throughout scientific labs.
- Infrastructure Shifts: Hospital laboratories (38%) and stand-alone scientific laboratories (30%) proceed to dominate diagnostic supply, aligning completely with Q-Line’s B2B mannequin.
- Regional Disparities: North India represents the one largest geographical market, commanding a 37% share of complete home IVD gross sales worth, primarily supported by excessive city healthcare penetration and public procurement through packages like Ayushman Bharat.
Q Line Biotech IPO Review: Financial Health
| Financial Metric | FY 2023 | FY 2024 | FY 2025 | 9M FY 2026 |
| Revenue from Operations | 182.74 | 203.65 | 313.78 | 232.42 |
| EBITDA | 32.98 | 37.63 | 71.32 | 64.23 |
| EBITDA Margin (%) | 18.05 | 18.48 | 22.73 | 27.64 |
| Profit After Tax | 32.10 | 34.45 | 28.13 | 38.69 |
| PAT Margin (%) | 17.56 | 16.92 | 8.97 | 16.65 |
| Debt-to-Equity (x) | 0.58 | 0.60 | 0.87 | 1.06 |
| RoE (%) | 25.20 | 21.29 | 23.74 | 16.88 |
| Return on Capital Employed (%) | 22.14 | 19.25 | 17.66 | 13.32 |
Q-Line’s operational well being is robust however presently leveraged. Shifting to high-margin in-house manufacturing boosted EBITDA margins from 18.05% (FY23) to 27.64% (9M FY26). While FY25 web revenue dipped resulting from short-term finance prices, it rebounded sharply to 16.65% by late 2025. Deploying INR 90 crore from IPO proceeds will quickly de-leverage the stability sheet.
Q Line Biotech IPO Review: Peer Benchmarking
There aren’t any listed company entities on both the mainboard or SME exchanges in India that present a direct, equivalent enterprise mannequin comparability for Q-Line Biotech. To carry out acceptable institutional benchmarking, traders should evaluate Q-Line’s monetary metrics towards outstanding unlisted market leaders throughout the medical units and IVD section.
| Company Name | Financial Metric | FY 2023 | FY 2024 | FY 2025 |
| Q-Line Biotech | Revenue Operating Margin (%) PAT |
₹182.7 Cr 18.0% ₹32.1 Cr |
₹203.6 Cr 19.0% ₹34.4 Cr |
₹313.8 Cr 18.0% ₹28.1 Cr |
| J Mitra & Co | Revenue Operating Margin (%) PAT |
₹160.3 Cr 40.0% ₹48.1 Cr |
₹193.6 Cr 42.0% ₹62.6 Cr |
₹201.8 Cr 37.0% ₹57.5 Cr |
| Transasia Bio-Medicals | Revenue Operating Margin (%) PAT |
₹1,445.6 Cr 3.0% -₹87.2 Cr |
₹1,524.3 Cr 10.0% -₹15.5 Cr |
₹1,401.6 Cr 17.0% ₹202.2 Cr |
| Molbio Diagnostics | Revenue Operating Margin (%) PAT |
₹332.5 Cr 13.0% -₹3.4 Cr |
₹836.6 Cr 22.0% ₹83.5 Cr |
₹1,020.4 Cr 24.0% ₹138.6 Cr |
| Agappe Diagnostics | Revenue Operating Margin (%) PAT |
₹390.5 Cr 11.0% ₹23.5 Cr |
₹442.6 Cr 9.0% ₹17.4 Cr |
₹516.8 Cr 13.0% ₹31.3 Cr |
Transasia Bio-Medicals (INR 1,401.6 crore) and Molbio Diagnostics (INR 1,020.4 crore) occupy a considerably larger tier of income scale. However, Q-Line has successfully outpaced J Mitra & Co in income measurement and matches the size of Agappe Diagnostics (INR 516.8 crore). Regarding profitability constructions, Q-Line’s present operational margin ranges (22.73% in FY25, accelerating to 27.64% in 9M FY26) sit comfortably forward of Agappe and Transasia, although J Mitra continues to steer the business section with an distinctive 37.0% working margin profile.
Q Line Biotech IPO Risks
While the top-line numbers, margin enhancements, and anchor backing current a compelling progress story, Q Line Biotech IPO evaluation reveals a number of vulnerabilities that traders can not afford to miss.
- Contingent Liability: As of 9M FY26, Q-Line Biotech carries an mixture contingent legal responsibility of INR 61.64 crore. This represents a 155% of the corporate’s web revenue generated throughout the identical 9M interval. Most critically, INR 46.05 crore (74.7%) of this legal responsibility consists of company monetary ensures prolonged by Q-Line to group entities and promoter-owned partnership companies, particularly POCT Science House Private (INR 15.00 crore) and POCT Services (INR 31.05 crore).
- Geographic Concentration Risk: In FY 2025, Uttar Pradesh accounted for 72.25% of complete gross sales, a dependency that heightened to 75.12% (INR 174.59 crore) within the 9M FY26. Any adversarial shifts in UP’s native healthcare coverage, revisions to state public procurement contracts, or regional provide chain bottlenecks current a disproportionate menace to company revenues.
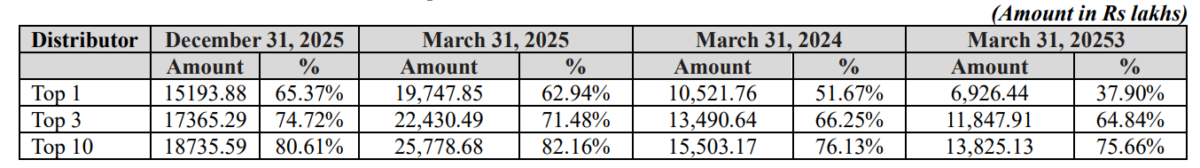
- Distributor Concentration: As on 31 December 2025, Q Line has 283 distributors, out of which prime two distributors contribute 72.4% and 68.19% of the gross sales for the interval ending 9M FY26 and for FY25 on a consolidated foundation. Further, one of many firm’s distributors, which can be a gaggle entity, POCT Services, contributes greater than 60% of its gross sales.
Verdict
Q-Line Biotech presents a robust basic proposition. The firm is working with important coverage tailwinds underneath the “Make in India” initiative, and its ongoing transition from low-margin product buying and selling to high-margin indigenous instrument manufacturing is clearly seen in its increasing EBITDA margins, which climbed to 27.64% in late 2025.
However, the funding structure is tightly coupled with important structural vulnerabilities. The excessive focus of income inside a single state (Uttar Pradesh, 75%) and the acute dependence on simply two distributors for over 68% of gross sales means the enterprise lacks systemic diversification.

Rajat Bhati has a robust technical background and 5 years of expertise within the inventory market. He focuses on fairness analysis, technical evaluation, IPO valuations, and danger administration, serving to traders make clearer, data-backed selections. Today, he works full-time to coach folks in regards to the alternatives in IPO market.
Source link
#Line #Biotech #IPO #Analysis #Indias #Biggest #SME #Issue #Avoid #Apply


