
 0
 0
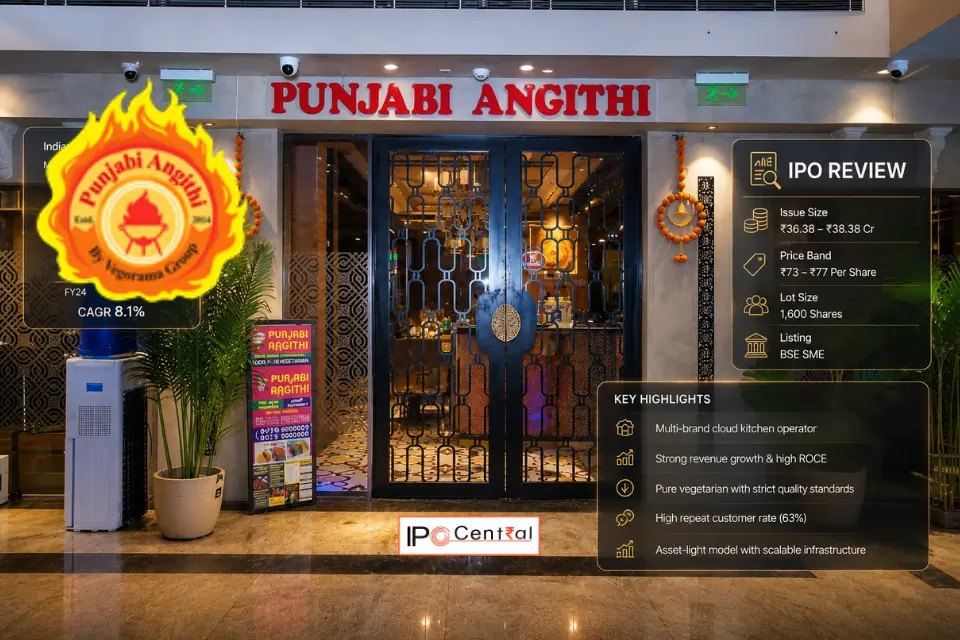
The Indian meals companies sector is present process a fast transformation, pushed by digital adoption, altering client demographics, and the proliferation of meals supply aggregators. Against this backdrop, Delhi-based Vegorama Punjabi Angithi is making ready to capitalize on this pattern. Founded in 2014, the corporate has scaled from a single cloud kitchen right into a multi-format, pure-vegetarian meals companies firm.
While the corporate’s monetary trajectory reveals aggressive topline development and distinctive return ratios, a better examination of its Red Herring Prospectus (RHP) reveals vital operational dependencies and company governance dangers. Vegorama Punjabi Angithi IPO evaluation dissects the information to supply an goal evaluation for potential traders.
Vegorama Punjabi Angithi IPO Snapshot
- Issue Dates: 20 – 22 May 2026
- Price Band: INR 73 – 77 per share
- Total Issue Size: INR 36.38 – 38.38 crore (49,84,000 shares)
- Lot Size: 1,600 shares (Minimum funding: INR 2,46,400)
- Listing Platform: BSE SME
Vegorama Punjabi Angithi IPO Review: Industry Overview
To perceive Vegorama’s potential, it’s important to contextualize the broader market dynamics. According to the National Restaurant Association of India (NRAI) and Indian Food Services Report (IFSR) 2024, the Indian meals companies trade was valued at INR 5.69 lakh crore in FY24 and is projected to develop at an 8.1% CAGR to achieve INR 7.76 lakh crore by FY28.
This development is essentially fueled by the fast enlargement of branded meals chains, cloud kitchens, and the deep penetration of meals supply platforms like Zomato and Swiggy. The market share can be anticipated to develop from 43.8% in FY24 to 52.9% by FY28. Cloud kitchens provide a definite aggressive edge. By eliminating front-of-house actual property, inside decor, and huge service groups, operators can obtain profitability sooner and scale with minimal capital expenditure.
Vegorama operates totally on a delivery-first cloud kitchen mannequin, supplemented by a current foray into advantageous eating. As of March 2026, the corporate manages 27 cloud kitchens (with two in Noida but to begin operations and one in Dwarka lately closed) and a pair of fine-dining eating places throughout Delhi NCR and Dehradun.
Key Operational Highlights:
- House of Brands Strategy: The firm makes use of a multi-brand setup working from shared kitchen infrastructure. Its portfolio contains Punjabi Angithi (flagship), Chinese Veg Crunch, Dilli Tawa Parantha, Food of Dreams, and Swaad of Punjab. This maximizes asset utilization and lowers mounted overheads.
- The Pure-Vegetarian Moat: Vegorama strictly adheres to a no-cross-contamination, 100% vegetarian preparation surroundings. In a market more and more delicate to dietary and moral meals decisions, this serves as a powerful differentiator.
- Digital-First Model: The enterprise generates over 91% of its income via on-line supply platforms. Despite the low model loyalty usually related to cloud kitchens, Vegorama maintains a sturdy 63% repeat buyer fee.
Vegorama Punjabi Angithi Financial Analysis
Vegorama’s monetary metrics mirror the inherent scalability and cost-efficiency of the cloud kitchen mannequin.
| Particulars | FY 2023 | FY 2024 | FY 2025 | 9M FY 2026 (Dec 2025) |
| Revenue from Operations | 16.88 | 65.95 | 101.31 | 105.05 |
| EBITDA | 1.16 | 6.04 | 10.86 | 12.40 |
| EBITDA Margin (%) | 6.88 | 9.17 | 10.72 | 11.81 |
| Profit After Tax (PAT) | 0.84 | 4.64 | 8.22 | 9.04 |
| PAT Margin (%) | 4.95 | 7.04 | 8.11 | 8.60 |
| ROCE (%) | 68.15 | 101.29 | 76.03 | 53.73 |
The firm’s income grew at a 81.71% CAGR in final 3-years whereas its EBITA grew by 110.71% CAGR. Vegorama’s EBITDA margins additionally improved from 6.88% to 11.81% throughout the identical interval. The excessive ROCE of the corporate (53% to 101%) highlights the capital allocation effectivity.
Vegorama Punjabi Angithi IPO Peer Comparison
To consider Vegorama’s IPO value of INR 73–77 per share (implying a P/E of ~11.21x to ~11.83x primarily based on FY25 EPS of INR 6.51), it have to be benchmarked in opposition to listed friends. However, traders should acknowledge the structural variations of their working fashions.
Operational Profiles:
- Vegorama Punjabi Angithi: B2C Cloud Kitchen heavy, hyper-local, aggregator-dependent supply mannequin.
- Speciality Restaurants: Capital-intensive, fine-dining and casual-dining heavy mannequin with 124 bodily retailers (e.g., Mainland China, Oh! Calcutta).
- Galaxy Cloud Kitchens: B2B Cloud Kitchen mannequin centered on personal labelling for retail, cafes, and QSR firms somewhat than direct client manufacturers.
- Vikram Kamats (Vidli Restaurants): Highway-focused, franchise-driven vegetarian QSR chain (37 out of 39 retailers are franchised).
Financial Comparison
| Company | Revenue (INR Cr) |
EBITDA Margin | PAT Margin | ROCE (%) | P/E Ratio |
| Vegorama | 101.31 | 10.72 | 8.11 | 76.03 | 11.8 |
| Speciality Restaurants | 413.08 | 21.68 | 5.19 | 9.76 | 19.3 |
| Vikram Kamats (Vidli) | 22.70 | 15.15 | 2.67 | 2.19 | N/A |
| Galaxy Cloud Kitchens | 15.23 | 17.61 | (21.60) | -16.62 | 70.4 |
Valuation Take: At the higher value band, Vegorama is valued at a P/E of ~11.8x. Compared to Speciality Restaurants buying and selling at 19.3x, Vegorama seems to be moderately priced. While its EBITDA margins are decrease than Speciality’s because of excessive aggregator fee bills, its capital effectivity (76.03% ROCE vs. Speciality’s 9.76%) is vastly superior, validating the monetary fringe of a cloud kitchen asset base.
Vegorama Punjabi Angithi IPO Risks & Concerns
Despite the robust monetary metrics, the RHP outlines a number of important danger components that traders should consider earlier than investing.
I. Pending Income Tax Investigation
The most urgent concern is an ongoing investigation by the Income Tax Department. The firm and its Promoters obtained summons beneath Section 246(2) of the Income Tax Act for monetary years 2020-21 to 2024-25. This investigation targets potential suppression of turnover and modification of billing data through ERP/POS accounting methods like Petpooja. While the administration has clarified that any variances come up from technical multi-entity aggregation, any hostile findings may result in materials tax calls for, penalties, and extreme reputational danger.
II. Platform Dependency
Vegorama is overwhelmingly reliant on third-party on-line supply platforms (Zomato and Swiggy). For the interval 9M FY26, ~91.93% of its working income (INR 96.57 Crore) got here through e-commerce portals. Food supply platforms usually cost excessive commissions ranging between 20% to 35% per order. Because Vegorama has minimal direct buyer acquisition infrastructure, any future hike in fee charges or change in platform algorithms will instantly squeeze its working margins.
Final Words
Vegorama Punjabi Angithi presents a compelling however high-risk funding proposition. On the constructive facet, the corporate has successfully scaled an asset-light framework, exploiting a pure-vegetarian area of interest to ship a powerful 63% buyer retention fee. The monetary translation is robust, that includes excessive income development, increasing working money flows, and superior capital return ratios. At an implied P/E of 11.8x, administration has left room on the desk for traders.
However, the dangers are closely back-ended. The Income Tax scrutiny introduces an instantaneous company governance overhang, and the 92% platform dependency means the corporate doesn’t absolutely personal its pipeline.
Rajat Bhati has a powerful technical background and 5 years of expertise within the inventory market. He focuses on fairness analysis, technical evaluation, IPO valuations, and danger administration, serving to traders make clearer, data-backed selections. Today, he works full-time to coach folks concerning the alternatives in IPO market.
Source link
#Vegorama #Punjabi #Angithi #IPO #Review #Growth #Sustain #Platform #Dependency #Risk


